Sunday, May 3, 2015

May 3, 2015, Bob Brinker's Moneytalk: Stocks, Bonds, Economic and Investing Summary

May 3, 2015....Bob Brinker hosted Moneytalk live today. (comments welcome)

"From the Sandwich Islands to Sandwich Mass, Moneytalk is unique."__ Bob Brinker

MAY MARKETIMER NOW AVAILABLE....Brinker announced this today.

STOCK MARKET

Today, Brinker commented that the S&P is very near its all-time-high -- and said that he recommends dollar cost averaging into equities for new money. He remains fully invested.

SELL BERKSHIRE HATHAWAY TO GET DIVERSITY AND DIVIDEND..
.. Caller Tom from Naperville said his aunt gave him 3 shares, worth about $216,000 per share, and wanted to know if he  should hold it or sell it.

Brinker replied:  If I'm starting out from a no tax liability standpoint, and if you haven't heard in stock, you should have a date of death value on it.  So if you inherited the stock yesterday the value of the stock would be the same as the date of death.  So then you would not have a tax liability because you would have the date of death cost basis.  If I were in that position, I would rather own something like the Total Stock Market Index or the S&P 500 for obvious reasons which would be diversification reasons.  And the other reason would be they pay a cash dividend.  You get a cash dividend of close to 2% on those holdings whereas you're not getting any cash dividend on the shares you own.  So I'd rather own a diversified, dividend paying security rather than just own shares of any one company including Berkshire.  (Tom would have a tax liability because he inherited the stock over 12 years ago.)  

CONSUMER SENTIMENT HIGH.... Brinker said: We've talked about consumer sentiment and how consumer sentiment has been firm.  University of Michigan Wolverine consumer sentiment index came out this week and it was unchanged – staying at 95.9.…  It's the highest level in three months.  Consumer sentiment has been helped by lower gasoline prices and fuel prices that place more spendable income in the pockets of consumers.  And yes, consumers benefit from that.

Honey EC: Expanding on Brinker's Moneytalk comments above:  In the May issue of Marketimer, which is now available, Brinker reviewed his stock market timing indicators. One of them is "Sentiment." 
Page 2;  Paragraph 6; Brinker wrote:  "Advisory service sentiment measures continue to indicate a high level of bullish investor sentiment.  This suggests that many investors are fully invested and that means potential demand may be reduced by relatively low stock market cash reserves.  In our view, the risk of a short-term correction is elevated due to the high level of advisory complacency.  In the absence of a major exogenous event, we would expect any short-term weakness in the near term to be limited to the single-digit percentage range.  The combination of low interest rates and the plethora of share buyback programs is likely to cushion any weakness that may develop near-term."
 FIRST FOMC 0.25% RATE INCREASE MAY NOT IMPACT BOND MARKET.....Brinker said:  When they (Federal Reserve) talk about a quarter percent, what they are talking about is that the expectation is, the first time that the Federal Reserve raises short-term interest rates – and that will be data dependent as chair Janet has said repeatedly (she said it again this week in her statement), that they expect that the most likely amount of the rate increase would be one quarter of 1%.  That doesn't mean that there would only ever be one one quarter of 1% rate increase.  It would mean that the expectation is that the first time the Fed raises rates – whenever that turns out to be – that it would be one quarter of 1%.  That may or may not turn out to be a factor in the bond market because it's such a tiny increase and it's coming off basically a zero level.  It may not have a whole lot of impact.

TWO CALLS, TWO OPPORTUNITIES TO BE HONEST ABOUT GINNIE MAE

VANGUARD BOND ETF (BND)...Caller Dave from Albuquerque said he owned BND wanted to know Brinker's opinion about the duration and told Brinker that he only cared about collecting the interest and didn't care about a net-asset decline if interest rates rise.

Brinker replied:  If you don't care about the underlying value of the portfolio – in other words it swings in either direction don't concern you one way or the other, if your only concern is getting the regular interest payments, then it doesn't make any difference to you what they price of the ETF is because you only care about the interest.  So is that the category you are in? (John: "Yes")  Well there you go.  You see I've said this before – for those who don't care at all that don't care at all about the underlying net asset value of the securities, they're only interested in the interest, then that is where the focus is.…  For my taste, 5 1/2 years is too long a duration.  It's not my recommendation.  It's certainly not my approach to fixed income at this time.  But if somebody doesn't care about the underlying value, it doesn't make any difference at that point.

Honey EC: Brinker laid the groundwork for the next call on Ginnie Maes -- putting the focus on John not caring about net-asset-value on a 5.6% ETF,  thus establishing a red herring so that he could talk about Ginnie Maes  as a comparison and avoid mentioning what a disaster it was for him to sell all Marketimer GNMA holdings in July of 2013 - Next call:

VANGUARD GINNIE MAE FUND (VFIIX)....Caller John from New York said that about 65% of his portfolio in VFIIX -- should he sell?

Brinker replied: They have a duration right now an average of 3.3 years.  So that's not a big number.  That's way different than our prior caller who doesn't care what happens to the net asset value in the terms of volatility.  He said that point blank when I asked him.  But his duration was 5.6.  Your duration is 3.3, which means you have much less volatility than a 5.6.  For every one point increase in corresponding rates, you have about 3.3 net asset value risk.  So in a situation like yours, where you are comfortable with the holding, we get back to the same question, how much do you care whether the net asset value of the security goes down?......

.....I would say this, you are comfortable with the holding, you don't seem to care a whole lot about net asset value fluctuation, you could have a capital gain if you're a long-term holder… Your duration is not much different than the duration I am recommending.  The duration I'm recommending is close to two and you are at 3.3.  So there isn't that much difference there.....The amount of risk that John is taking holding a 3.3 is basically if rates went 3%, he's taking a 10% price risk, but 3% would be a lot right now.....

.....The Federal Reserve is having a hard time raising rates at all.…  In order to get 3%, you'd have to have an acceleration in the economy – and we don't see that right now.…  You've been looking at zero interest rate since December 2008, and you've never had an acceleration of the economy.  Just about every single year you've had growth about two and a fraction… And the absence of that acceleration has been the reason that rates have been able to stay where they are.…  So I don't think  in John's particular case, it's a really big deal, especially given the fact that his duration is low to begin with.  Not as low as I would like but nonetheless it's low.

Honey EC: Spin, spin, spin.... Brinker used to reassure callers that the NAV of VFIIX would fluctuate between $9.50 and $10.50. That was before the NAV grew to over $11.00. Then he started telling people that if they couldn't tolerate price declines, they could use FDIC-insured CDs.   

Brinker held VFIIX until it dropped to $10.37 and sold all Marketimer holdings in July, 2013. He put that cash into Fidelity Floating Rate Fund.

VFIIX is now selling for $10.79 and still pays almost 3% dividend. And Brinker has now sold all FFRHX and returned to DoubleLine Total Return Fund (DLTNX) which he had sold for a much shorter duration fund.

GROSS DOMESTIC PRODUCT DOWN TO 0.2 in Q1 - HERE'S WHY....Brinker comments: The news has been coming fast and furious in terms of investments.  Not the smallest story of the week was something we predicted on last week's program, if you were with us.  And that was a lousy Gross Domestic Product report which came out at the end of the week.  Real GDP was up just 2/10 of 1% in the first quarter.  Certainly better than the first quarter of 2014 which was in negative territory – hold number territory.…

HERE'S WHY GDP REPORT WAS LOUSY.... Brinker continued: Couple of factors that jump off the page and one of them is weather.  We had one of the coldest February's of all time.…  I've said it before – the whole global warming thing, we are all going to freeze to death – just be patient.  Another factor in the first quarter which happily is no longer with us was the West Coast port strike.  We had an extended and extensive strike affecting the Long Beach California port....These factors are behind us and will not return soon.

ONGOING GDP KILLER - STRONG DOLLAR.....Brinker continued: A couple of other factors that are still out there and must be respected for what they are.  One of them is the strong dollar.  The greenback has just been on a tear and as long as there is this kind of strength in the dollar, US exports, when they go overseas on the shelves are more expensive.  Therefore, competitive products overseas have a better shot at getting the sale.  And there is also another issue which is the products imported into the US,  they are cheaper when the dollar is this strong. This gives those who import products the opportunity to be more competitive.

DECLINE IN OIL PRICES ALSO GDP KILLER.... Brinker continued: Now the other thing that has been going on is one that we have talked about many times, which is that the decline in oil prices has led to a decline in capital investment in the energy area – which has always been a very strong area in capital investment.  Yes we have seen a pretty good rebound in the price of oil back into the mid-to-upper 50s, up from the low 40s… But the reality is that the number of rigs that have come out of service in the past several months has been amazing.  The rate count is way down and that affects capital investment as well.

EXPECT BETTER ECONOMIC GROWTH IN Q-2.... Brinker continued: We should certainly expect to see some improvement in the second quarter real GDP numbers.  Remember what happened last year?  We had that really rough first quarter and then the economy rebounded quite well.  In the last year, real GDP has risen 3%.…  Which by the way is fairly close to the long-term growth track.  So on a 12 month basis, we've had a decent economy.

BRINKER'S FUN QUOTE OF THE DAY: "In my opinion, being on a golf course is as close to heaven as you are going to get on this planet."

JEFFCHRISTIE'S MONEYTALK FINAL EXAM QUESTION OF THE DAY:

Bob Brinker used which one of the following scandals to describe the current business news?
A) IRS abuse.
B) Fast and furious.
C) Benghazi.
D) Solyndra.

ANSWER  

Brinker's guest-speaker was Michael Casey: The Age of Cryptocurrency: How Bitcoin and Digital Money Are Challenging the Global Economic Order

Note: Frankj thought this guest was boring (several others agree with him), so he didn't summarize the third hour. However, Brinker had another guest on talking about Bitcoins in July of last year. Frankj did a summary. You can read it HERE.

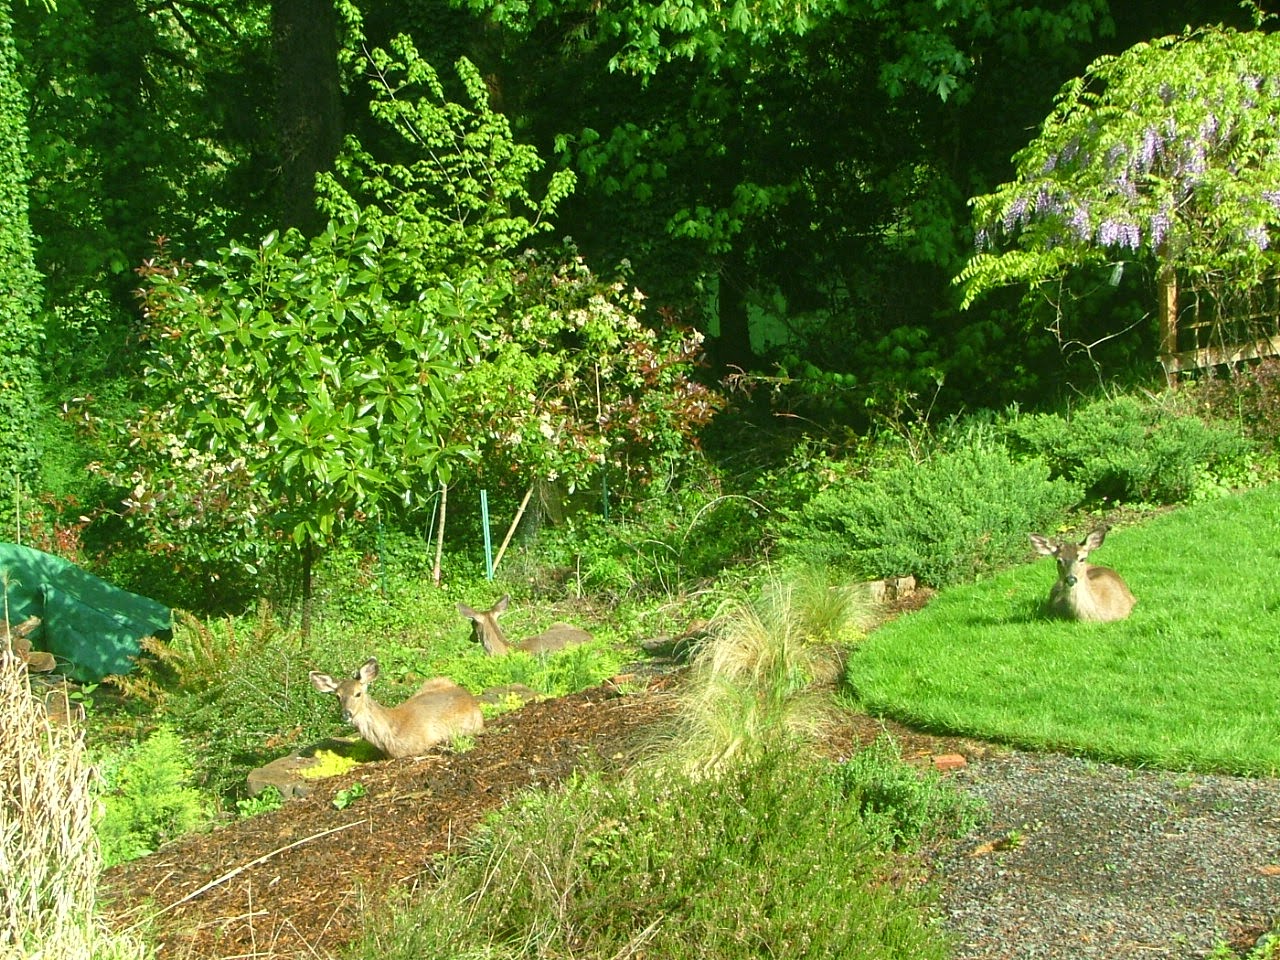
Frankj sent a picture of his three visitors. Notice the beautiful Chinese Wisteria tree in the background. I'm sure his special cat, Hobbes, was somewhere nearby when this was taken. 


Summary posted at 7:06pm PDT
READ AND POST COMMENTS

Sunday, April 26, 2015

April 26, 2015, Bob Brinker's Moneytalk: Stocks, Bonds, Economic and Investing Summary

April 26, 2015....Bob Brinker hosted Moneytalk live today......(comments welcome)

STOCK MARKET....Brinker told a couple of callers that he was "comfortable" with them having their full stock allocations invested. Several callers today asked questions pertaining to the stock market -- which I have covered below.  Brinker's answers indicate that he is still fully invested and bullish.

STOCK MARKET FLASH CRASH..... Brinker comments: Big news this week about the 2010 flash crash.....It was a big deal because it had a big impact on many retail investors.....It was basically an event where about $1 trillion in stock market value was erased in a matter of minutes.…  There was a 36 minute period, starting at 232 Eastern time in which the market had a collapse and rebound the likes of which has never been seen in such a short period of time.  The velocity of price action was mind-boggling....At its intraday low point, the Dow was down 998 1/2 points, or at that time was about 9% of its value in a matter of a few minutes.  Now much of that loss was subsequently recovered but it was the second largest point swing of all long time.

Here is the link to the article that I posted in comments last week: Trader Arrested in Manipulation That Contributed to 2010 Flash Crash

STOCK MARKET FALLOUT FROM FLASH CRASH....Brinker continued:  And a lot of fallout came after this and was unfortunate because there were people who looked at the flash crash and said, you know what, that's not for me.…  And that's why stock market investors pulled out about $25 billion from the market right after the flash crash.  And that's why mutual investors pulled out almost $100 billion from US stock funds over a period of about eight months – week after week....And when the investigation was held as to what had happened, well people were not satisfied.…

HIGH-FREQUENCY TRADER ARRESTED.... Brinker continued: As of this week we have a new explanation because the Commodities Futures Trading Corporation, along with the Justice Department, claim claim that a 36-year-old London high frequency trader made $40 million from 2009 on by programming and illegally manipulating the futures market – specifically what is known as the E-mini futures market.  He's accused of doing this by making it appear that there were more sell orders than by orders.  There's a Wall Street term for this and that term is layering.  But in the case of this individual, the layering was a little different because he had the ability through his computer set up to cancel old orders and add new orders so fast that the sell side pressure went on and on and on.…

PANIC STOCK MARKET SELLING FOR WEEKS.... Brinker continued: Following this catalyst there was a selling panic on the stock exchanges. So this is the latest twist, if you will,  on the flash crash....For all of that money, over $100 billion, to get subsequently withdrawn from the market.

STOCK MARKET SUBSEQUENTLY WENT STRAIGHT UP.... Brinker continued: It's a shame because look what the market is done since then… Since that time of the flash crash the market has soared – it's skyrocketed.  And from that point on, with an exception of a correction in the summer of 2010, and a correction in the autumn of 2011, the market has almost been straight up.  Yes there have been correction but not big corrections.  The biggest correction cents the autumn of 2011 on a closing basis in the S&P 500 has been 9.9%.  And we only had one of those.

 WHATTA SHAME INVESTORS GOT SCARED OUT.... Brinker continued: So it's very unfortunate that this happened, because a lot of people left the market as a result of it and never came back.  And therefore have missed out on gargantuan stock market gains in recent years.  And that's a shame because you don't like to see people missing out on giant stock market gains – especially for a reason like this.…  This is not a good reason – because somebody is playing computer games and manipulating prices.  That is not a good reason to get shaken out of the market.  But it happened to a lot of people and that's most unfortunate.

Honey EC:  Brinker needs to take some of the blame for people getting scared out, and being afraid to get back in. For a couple of years now, he has been very been negative because of the lack of corrections -- issuing warnings and cautioning listeners and subscribers about being "vigilant," only dollar-cost-averaging "on weakness," which never came. 

SOLID PENSION AS FIXED INCOME PORTION OF PORTFOLIO....Caller Frank from Michigan said: "I get a pension, like a regular pension that people used to get in America.  And I was wondering, can I count that as, I have a 401(k), and I have almost 100% in the S&P.  Can I say that my pension is balancing my risk?"

AT 100% STOCKS EXPECT VOLATILITY..... Brinker replied: If you're going to stay invested all the time, the one thing you have to accept is a lot of volatility.  It's not always going to be like the last six years which is been pretty rosy for the stock market.  It's not always good to be like that so if you're going to maintain that regardless you're going to have to accept the volatility.

COUNTING ON BRINKER FOR STOCK MARKET WARNING.....Frank followed up: "I was hoping I'd get a news bulletin from you like I did – not the last bubble, but the one before that, the tech bubble."

Brinker replied: "That would be wonderful.  That would be wonderful.  I agree with that."

Honey EC:  It's shocking that so many people believe that Brinker called "a tech bubble" in 2000. Just the opposite, he was advising buying with cash reserves that he had raised from model portfolios as the Nasdaq dropped about 70%. I have covered this before, but he only raised 65% cash from equities in 2000 and put much of those cash reserves back into QQQ and lost 70% of it -- with a special bulletin that Frank mentioned.

COUNT PENSION AS FIXED INCOME.....(after finding out Frank's pension was secure Brinker continued):  If you would count that $50,000 a year as $1,000,000 dollars in the bond market yielding that, you would have an equity ratio of less than 25%.…  I mean if you look at the where yields are today.…  You could do it in a diversified way with high grade bonds.  You'd have to be way out on the maturity scale so you'd have to hold them to maturity because rates being as low as they are now.  They're not going to stay here forever.…  If you want to look at it that way, now, you could do it.  Some people would say, you have $400,000 in the stock market and you have nothing in bonds.  But you could say, I have $50,000 in annual solid, annual pension income.…  If you woke up tomorrow and your 400,000 was worth 200,000 because people thought the world was coming to an end, it wouldn't really change anything for you – you'd still have your pension so that's why I think you can get away with it. 

HOW WILL THE STOCK MARKET REACT WHEN FED RAISES INTEREST RATES.... Karl from Chicago wanted to know when the fed would and how the Fed would interest rates and would it shock the stock market.

Brinker replied:  I think that the markets understand that the Federal Reserve eventually will move in the direction of normalizing rates.  I think that the markets are learning that the Federal Reserve, as you said, are very nervous about the notion of raising interest rates.  And the reason that they are nervous is because they realize that the economy is growing very slowly.  We are going to get a lousy, with a capital L, report on first-quarter Gross Domestic Product next week.…  The Fed knows all of this.  The theory is that the economy is going to do better the next to the year – and I think that is a reasonable assumption at this point.

25 BASIS POINT INCREASE WON'T CHANGE ANYTHING...Brinker continued: But let's face it, a 25 basis point increase in the federal funds rate is not going to change anything.  It's not going to slow down the economy.  It's not going to have a dramatic impact on intermediate and long-term rates.  It's the first baby step toward normalization.

FEDERAL RESERVE HAS A STOP AND START POLICY...Brinker continued: And now we also know that the Federal Reserve has a stop and start policy that they are willing to implement, which means that if they raise rates 25 basis point at a meeting, that does not mean that they are going to do it every meeting.  They are willing to stop and start – monitoring the economy is.  Also remember that the Fed knows if and when they increase rates in the current environment, they are doing the opposite of what other countries are doing.  The European Union is easing.  Japan is easing.…

FEDERAL RESERVE IN A TOUGH SPOT...Brinker continued: I think that they are caught in a tough spot because I think they really would like to increase rates very very much.  There's no question in my mind that they would be much happier if they could increase rates – get toward normalization because they believe that it gives them more flexibility than having a zero rate policy.  They have this zero rate policy that when an in December 2008 and they been stuck with it every sense because they haven't been able to do anything about it.  So they had to invent a new easing policy known as quantitative easing – which they did.  So they feel like they would like to have rates go up so that they could bring rates down if they had to – but they're afraid to put rates up because the economy's been fragile and now we're going to see a lousy first-quarter number.…  On the other side of the coin, is the fact that the Federal Reserve has the ability to keep rates down because there is no inflation.  The year-over-year CPI is negative – 0.1.…

NO CHANCE OF FED RAISING RATES NEXT WEEK....Brinker said: "I would say there is no chance that the Federal Reserve will raise rates at this week's upcoming meeting and they are going to remain data dependent – just as they have said."

$18 TRILLION NATIONAL DEBT ....Caller Bruce from Milwaukee said: "The United States has $18 trillion in debt now and we keep electing politicians that don't balance a budget.  How much more debt in the US handle?"

NATIONAL DEBT NO PROBLEM WITH 3% GDP.....Brinker replied: I think the answer to your question is, I think the country can handle debt that is less than 3% of Gross Domestic Product in annual interest serviced, which is where we are now.  We are at two and a fraction.…  As long as the economy is growing.  But I think that when the debt service becomes more than 3%, then I think we have a growing problem.

POLITICIANS DON'T ADDRESS PROBLEMS.... Brinker continued: You are correct, we do have politicians in Washington that are not addressing the future.  They have failed to address the infrastructure in our country… They have failed to address the problems with Social Security and worst of all, they have failed to address the Medicare problem – the imbalance in future Medicare expenses and income.…  They're not addressing it because it's unpopular politics… It's not a good way to get elected.  And politicians like to get elected – they don't like to spend money and time losing.  Why do the voters let them get away with it?  That's a very good question.…  I don't see any prospect right now of balancing the budget… Especially with the slow growth that we have.…  Were already controlling spending quite tightly on a year-over-year basis.  So I would say with moderate growth even, I don't see that we're going to balance the budget.  Do I think it's important?  No.  As long as we keep the interest service below 3% of GDP on a annual basis.…  But I think the bigger problem is, as we go forward the deficit is going to increase.

Honey EC: Brinker's choice about what needs to be addressed in Washington D.C. is very subjective. I can think of several things that are much more critical to the national debt.

ECONOMY....Brinker said: "We are going to get a lousy, with a capital L, report on first-quarter Gross Domestic Product next week.…"

THERE IS NO INFLATION...Brinker said:  "On the other side of the coin, is the fact that the Federal Reserve has the ability to keep rates down because there is no inflation.  The year-over-year CPI is negative – 0.1"  and he commented that inflation is very low everywhere except San Francisco where it is 2 1/2%.

NASTY CALL OF THE DAY....Caller Joe from Florida said that brokers and fund managers were just below child molesters. Brinker replied that there was no hope for him if he believed that.

Frankj's Third-Hour Guest Summary:

Bob interviewed Paul Sullivan a New York Times columnist and author of the book,  The Thin Green Line: The Money Secrets of the Super Wealthy

The Thin Green Line, The Money Secrets of the Super Wealthy. Paul said he wrote the book because he wanted to see how he and his family could get on the “wealthy” side of life.

He lunched with a group of wealthy people who meet once a month. To be part of this elite group you need at least $10 million in assets and you also have to be willing to pungle up $30,000 a year to pay for lunch. Paul said they don’t trade stock tips or estate strategies, they talk about more weighty issues like how wealth will affect their kids and grandkids, how to deal with charities.

With regard to charities, the guest said the very wealthy grapple with problems on how to give money away so their giving is effective. An eBay co-founder worth 8-9 billion is trying to give money to educational causes but wants to know his giving will have a measurable effect. He cited John Huntsman Sr., a multi-billionaire who regularly tips with $100 bills. Mr. Huntsman supports cancer research.

Bullet points:

· Don’t fret over taxes. Don’t cheat. Taxes are what we pay to live in a free society. He cited an example of a rich guy who put money offshore and ended up paying much more when caught, and, the financial guy who facilitated it got jail time too.

· If you have young sprouts, age 3 to 8 that is the time to teach them perseverance and resilience two traits that will serve them well.

Tim in Honolulu asked whether the wealthy subjects of the book had opinions about the student loan bubble. Sullivan said this was not a topic but Tim’s question opened the door to discussion. Paul said at age 17 – 18 students are not in position to understand the implications of how student loans can affect one’s life. Bob weighed in with his mantra that college should be free in the US. The guest said something that I think was very important (paraphrasing): Four years of college will not determine what type of person you become intellectually, but the debt you incur can determine a great deal about your life after college.

Bob and the guest proceeded to beat up on institutions that seem to build up endowments just for the sake of doing so. Sullivan said that colleges will sometimes pay the tuition for a top student whose family is below some income level but they still want students who pay the full ride, either from Mom and Dad’s bank account, or from loans. Some with huge endowments could give everyone a free ride if they chose to.

Bill in Omaha asked whether Dems or Repubs give more to charity. Paul Sullivan didn’t deal with that in the book, he said they give to different charities.

Paul Sullivan went to Kansas State and got wired up with some electrodes to take a stress test on money. He learned he is “money vigilant,” meaning he is aware of incoming and outgoing, and this can sometimes affect decisions and you end up depriving yourself of something you can actually afford.

Other categories include money avoidance (don’t want to think about it); money worship, money status (your self worth = money).

Here is a link to this work, it is a scientific paper but you can read about these “money scripts” starting about 14 pages in.

Psychology Today:money-beliefs-and-financial-behaviors-development-the-klontz-money-script-inventory-jft-2011.pdf

Bob wound things up at about 3:50.
 
Jeffchristie's Moneytalk Final Exam Question of the Day.....

Bob Brinker said that the 2010 flash crash was caused by:

A) The Koch brothers.

B) A trade entered by the money manager of the Clinton foundation.

C) A 36 year old Indian trading in London.

D) A sell signal issued by a newsletter writer.

ANSWER

Summary posted at 7:05pm PDT
READ OR POST COMMENTS

Sunday, April 19, 2015

April 19, 2015, Bob Brinker's Moneytalk: Stocks, Bonds, Economic and Investing Summary

April 19, 2015....Bob Brinker hosted Moneytalk live today....(comments welcome)

I want to sincerely thank Jeffchristie and Frankj. for coming to my rescue while I spent time with family who were here visiting from Utah.

Jeffchristie's First-Hour Moneytalk summary:

Bob started with the standard opening. Become your own financial manager etc. He spent the rest of the first segment talking about Greece.  The new government ran on unrealistic reforms.  The current bailout  from the EU is valued at a quarter of a trillion dollars. The way Greece is going, Bob does not see how they can pay it off.  Will Greece remain in the Euro or print their own money?   Will the government and the banks default on their loans?  We shall know in the fullness of time.

Joe from Fort Lauderdale wanted to know if he should include the required minimum distribution from  his IRA as part of his annual  4% withdrawal.  Bob said he didn't have a problem with that. 

Bob from Missouri, a Marketimer subscriber, has his ROTH IRA in Portfolio 1 and his income producing assets in a taxable account.  He wanted to know if he should swap.  Bob told him to look at the tax consequences.  In general Bob said he felt it is better to keep the income portion of your portfolio in a tax privileged account.

Clay in Medford Oregon wanted Bob to tell him what the future exchange rate would be for Bit coins vs. the US dollar.  Bob told him that Bit coins were extremely volatile and no one can predict their future.

Rowan in Illinois wanted to know if he was at critical mass.  He inherited a rental property from his mother and he also has Social Security and another monthly disability payment.  Bob said that critical mass was having enough income to live on without requiring you to work.

Richard in Maui said it was too hot for him there in the summer time and he was looking at a place in Catalina.  He was thinking about selling a rental property .  As they talked through the tax consequences he decided it would be better for him to rent in Catalina.

Nathen  in San Diego  had rental property  he wanted to sell.  Bob sais he should look at a 1031 like kind exchange.

Clarence in Utah had several hundred thousand dollars that he was considering investing in gold and silver.  Bob said he didn't own either and advised against it.

Kevin in Indiana wanted advice on an annuity.  Bob advised against it.

FrankJ's Second-Hour Summary

China is easing its monetary policy, announcing a reduction of 1% in the reserve requirements for lenders. The accommodative policy sets the new reserve requirement at 18.5%.

A study conducted by Morningstar and published on April 13th in the New York Times compared the mutual fund performance of funds owned by investment banks like J. P. Morgan and Goldman Sachs with Vanguard. The investment bank funds underperformed their benchmarks. The managed funds at Vanguard outperformed 80% of their peers over the last decade.

Vanguard emphasizes its index funds, but they do have some very good managed funds with low expense ratios.

Bob then went to calls, beginning with Estelle from WLS Chicago country. She is 86 and is widowed, with about 500 thousand at Vanguard and 1.5 million in laddered CDs. Bob advised her to move the CDs over to Vanguard and get their help with reinvesting as they mature.

Lee from Iowa is trying to get his portfolio configured to be like Bob’s Portfolio III. He has money in a REIT mutual fund that is worth $35,600. And he has $112,000 in GNMAs and I Bonds. Bob advised him to go 50% equity and fixed. Bob made no comment on the GNMAs. It sounded like Bob was OK with the REIT allocation as long as Lee was.

Next up was George from Illinois. I did not catch whether he said he was a long time listener, but based on his question, I would be surprised if he was: “I have my IRA at a bank that is charging me a 2% management fee, I am thinking of moving it to a brokerage firm where I’ll have more choices.” Bob cut to the chase and told him to move it to a large no-load outfit like Vanguard or Fidelity. George asked about Schwab and Bob said, “sure,” Vanguard is my first choice but you can use Schwab, Chuck Schwab has been a guest on the show.

Bob got back into the Greek Tragedy with caller Alan from Missouri who wanted to know the short term (2-3 month) effect on the stock market if Greece is kicked out of the Euro. Bob brushed off any effects and went into a rant against the Greek leadership and the people who put them in power that ran the clock down to the bottom of the hour.

After the half hour break, Christopher from Charleston called with a long, sad story about his daughter’s foray into gold investing. From the sound of it, she got scammed BIG TIME. She invested $7500 when gold was trading at about $790 per ounce. Instead of getting the actual metal, she got certificates. Then after it had doubled in price she tried to cash out and ended up with only $2900. Bob called the whole thing a scam. Coincidentally, on the station I was listening to, WLS Chicago, there was an ad for gold investments at the close of the second hour.

Social security came up a couple times in the second hour. Tony from Texas and his wife are approaching age 62. They have a couple of adopted kids under 18. Tony heard that you could get additional money from Social Security for these 2 dependents. Bob rightfully referred him to a local office of the SS Administration. A caller from Fairbanks wanted to know the future for SS. Bob said he thought those receiving benefits now are OK, but long term changes are needed. The system is very generous which makes it “unsound” long term considering fewer workers are paying in per recipient.

I thought one of the more interesting calls came from Carey in Illinois who asked Bob about the most recent jobs report and its effect on the market. Bob said that the S&P is now over 2000 (at 2081) and back in early 2003 there was a buying opportunity in March when it was at 800.

He said, “yeah, there was a lot of volatility in 2008 but it came and went.” This was about 45 minutes into the 2nd hour if anyone wants to hear this dismissal of the market meltdown with their own ears.

(Honey here: Frankj dropped me an email and told me that I needed to carefully listen to Carey's call and Brinker's reply, which was truly astonishing. I transcribed it and posted it below.)

Bob went on to explain the jobs report as being affected by cold weather, the West Coast port strike in Long Beach. But these have “come and gone.” Still with us is a weak energy sector and strong dollar.

Another interesting call came in from David in Michigan who gets income from SocSec and has a portfolio of individual stocks worth $250,000 in total. Bob quizzed him on the largest holding and David said about $5000. He inherited these and there are considerable capital gains if sold. He wants to gift the stock to a daughter. David seemed to favor selling them and booking the gain and buying them back, then giving or willing them to his daughter with a higher basis. He thought he would not actually have to pay much or anything in tax on the gain since his income was low and consisted of SocSec only. Bob mentioned gifting and David’s 5 million dollar lifetime exclusion on gifts.

If he gifts shares to his daughter, a bit at a time, there are no tax consequences for him, but she takes on his low cost basis, so if she sells, she might have a big capital gain tax hit.

If she inherits after his death, then she gets a stepped up basis, that is the value of the stock on the date of death or 6 months after becomes her basis.


Patricia from Novato CA wanted to know what effect China’s decision to change its reserve requirement would have on the world at large. Bob said “It is Sunday, it just happened!” So, no prognostications were forthcoming. Then she asked for the title of a book she could read to understand bonds better. Bob recommended one from the reading list called The Bond Bible. Another one is by Larry Swedroe, The Only Guide to a Winning Bond Strategy You'll Ever Need: The Way Smart Money Preserves Wealth Today.


Frankj's Third-Hour Guest Summary:

Bob’s third hour guest on April 19th was Ben Parr, author of the book,  Captivology: The Science of Capturing People's Attention

This is going to be short because I found the topic boring but that’s just me. Also, the interviewee must have been calling on a cheap phone, or using a can with a string attached because some of the interview was hard to understand.

Capturing people’s attention is important to anyone who wants to sell stuff, particularly startups. One of the ways you do it, capture their attention, and retain it, is to violate people’s expectations. Two TV shows were mentioned, The Sopranos and Curb Your Enthusiasm. In fact they spent a lot of time talking about TV shows, series and media. Breaking Bad was another example of a show that violated our expectations.

There had not been a similar story line in anything previously. It became a mystery for viewers as how Walter would keep going, so that kept people watching. And, we were interested in looking at a world that most of us would never be part of.

This author identified three “stages” of attention. Immediate, like when a car backfires. That gets your attention but only momentarily. Then, short term, like a song you like from an artist. Then, long term, when you go out and buy everything that particular artist ever released.

The guest said that inattention can result when you are trying hard to keep the audience’s attention. He cited a teacher giving a Power Point presentation with imagery on the slides, bullet points on the slides, and at the same time, explaining the slides. The children get distracted looking at the slides and bullet points and don’t hear the teacher. Just put an image on the slide and drop the bullet points.

He linked the “violates our expectation” concept to humans once being hunters and gatherers where paying attention could be a matter of survival. This is why we take notice of stuff in our everyday lives that is unexpected or out of place. Is that clown that just came through the door at Starbuck’s a threat? That kind of stuff.

Honey here: I agree. I heard the last half hour and found the guest-speaker boring, but Frankj found some interesting points anyway. :)

The following is a transcription of Brinker's 2008 "volatility" and "dollar-cost-averaging opportunities" in 2008. The call was 45 minutes into the second hour: 

Caller Carey said:  "My question is with the weaker jobs creation the last time they reported it, and the lower long-term rates which I think in the past you have said where significant, and now that China has eased further, what are your thoughts about the markets going forward.  Is it time to add additional money or are you becoming a little more cautious at this point."

Brinker replied: "We are already fully invested.  We have been fully invested since the S&P 500 was basically at the 800 level.  We took the money out early in the last decade and put it back in March 2003, we put it all back in – the S&P was around 800.  Now the S&P is over 2000 and we've been fully invested during that entire period.  Obviously, it's been an incredibly rewarding run.  Yet it was a lot of volatility in 2008, but it came and it went.  In fact it provided additional dollar cost average opportunities throughout that period.

Honey EC: For those of you who have been following Brinker since 2000, please bear with me while I review the FACTS that Brinker either FORGOT or? You be the judge. 
 1. Brinker SAID: "We took the money out early in the last decade and put it back in March 2003. The S&P was around 800.  Now the S&P is over 2000 and we've been fully invested during that entire period.  Obviously, it's been an incredibly rewarding run." 
 Truth: Brinker took out a total of 65% from equities in his model portfolios in year 2000  and  put  it back in March 2003 -- where it has been ever since. 
2. Brinker SAID: "Yet it was a lot volatility in 2008, but it came and it went. In fact it provided  additional dollar cost average opportunities throughout that period."
 Truth: SAY WHAT? Did Brinker really ignore the fact that the S&P did another complete round-trip to BELOW 800 in 2008-2009?  The S&P was at 800 in March 2003, but it had climbed to over 1500 in October 2007, then dropped to a low of 677 in March 2009!   
3. Brinker said:  "In fact it provided additional dollar cost average opportunities throughout that period."
Truth: I'm just suuurree that Brinker simply forgot all the gift-horse buying opportunities that he put out during 2008 as the market dropped. 
 In 2008-early 2009 Brinker called several "buying opportunity" bottoms. Yep, that's it, he just forgot. Here's the list of them:
  • January 4, 2008, S&P @ 1411: "Mid-1400's"
  • Feb 10, 2008 S&P @ 1331: "Low-1300's" (delivered via "special bulletin" - no mention of January Marketimer mid-1400's buying opportunity)
  • Aug 5, 2008 S&P @ 1285: "1240 or less"
  • Sept 2, 2008 S&P @ 1282: "Low-to-mid 1200's"
  • September 16th -- rescinded low-to-mid 1200's (recommended dollar cost-average only)
  • January 2009 S&P @ 931: “bear market bottom range of 750 to 850."
  • Feb. 2009 S&P @ 826: “low-to-mid 800’s"
  • March 5, 2009, S&P @ 696: said waiting for a "bottom and a test of that low." NO DOLLAR-COST AVERAGE IN MARKETIMER or buy levels.
Jim explains another Truth that Brinker "just forgot":
Blogger 
 Jim said...
I was so shocked hearing Brinker describe 2008 as merely "volatility" that I missed the lie about putting ALL of his money back in during 2003. You can't put ALL the money back in unless you had already taken ALL the money out. As we know after taking only 65% out he told aggressive investors to put half back into QQQ shares. So those people only had 32.5% left to put back in during 2003. 32.5% is far from being ALL the money.

April 20, 2015 at 8:24 AM
Delete
 Jeffchristie's Moneytalk Final Exam Question:

How many times has Greece defaulted on its sovereign debt since 1800?

A) Three B) Four C) Five D) Six

ANSWER

Summaries Posted at 7:55pm PDT
READ AND POST COMMENTS